Schedule A Irs 2027 Explained: A Clear Path to Maximizing Your Deductions
Cracking the Code of Schedule A IRS 2027: What You Need to Know
Ever stared at your tax forms and felt like they were written in some alien language? Schedule A IRS 2027 might just be that mysterious puzzle for many. But once you get the hang of it, it can seriously slash your tax bill.
What you’ll learn: How Schedule A IRS 2027 works, what deductions qualify, and insider tips for making the most out of your itemized deductions. Additionally, dc schedule h covers similar aspects.
📌 Quick Summary: Schedule A IRS 2027 is the form that lets taxpayers itemize deductions instead of taking the standard deduction. It’s crucial for anyone with significant deductible expenses, like mortgage interest or medical costs. Understanding this form means keeping more of your hard-earned money in your pocket.
Inside Schedule A IRS 2027: Breaking Down the Deduction Categories
Medical and Dental Expenses
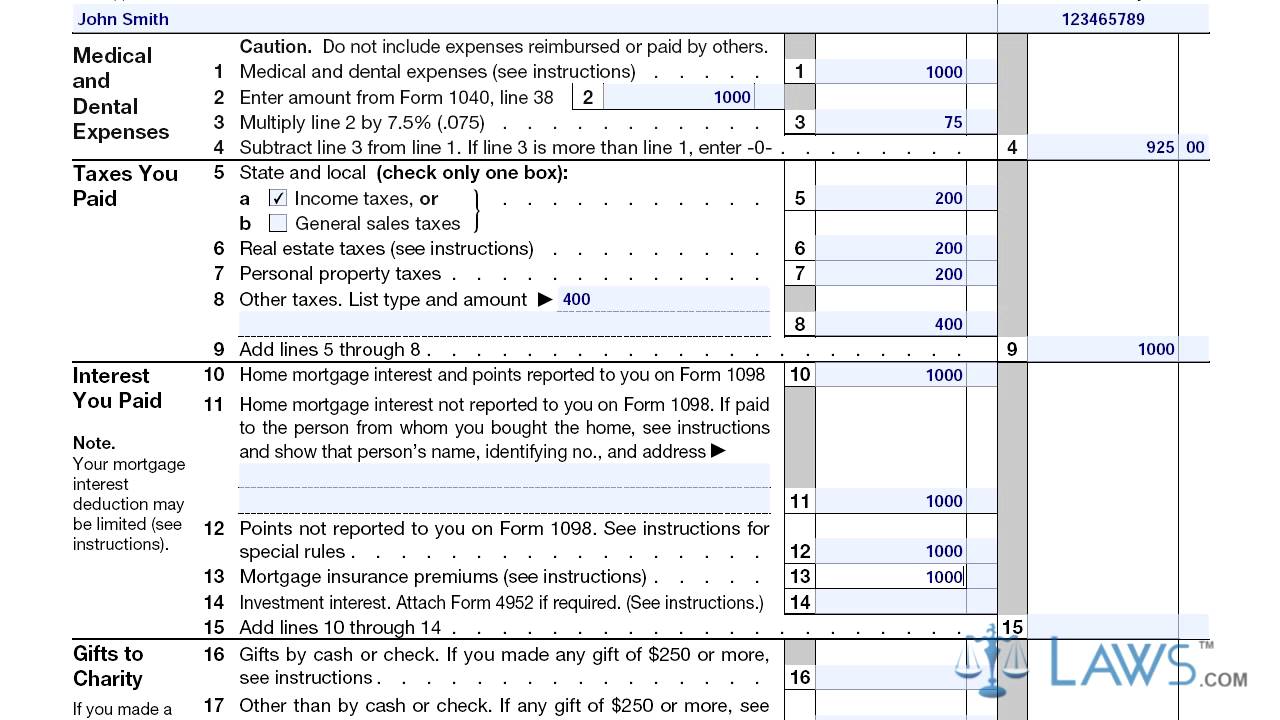
Medical bills can pile up fast—think doctor visits, prescriptions, and even some long-term care costs. For Schedule A IRS 2027, only the part that exceeds 7.5% of your adjusted gross income (AGI) counts. That’s a steep threshold, but if you’ve had a rough year health-wise, it pays to itemize.
Pro tip: Keep every receipt. I once helped a friend recover thousands by carefully tallying every co-pay and unexpected expense from the previous year.

State and Local Taxes
Here’s where things get interesting. You can deduct state income or sales taxes, plus property taxes—but there’s a cap: $10,000 total. If you live in a high-tax state, this limit can feel like a slap in the face.
Remember, choosing between deducting sales tax or state income tax depends on which benefits you more—run the numbers before you check the box. Additionally, cfp schedule covers similar aspects.
Mortgage Interest and Investment Interest
Mortgage interest deduction remains a favorite on Schedule A IRS 2027. Interest on up to $750,000 of mortgage debt qualifies for homes bought after December 15, 2017. If your mortgage is older, the limit is $1 million. This little detail can save you thousands.
Investment interest? That’s interest paid on money borrowed to buy taxable investments. It’s not for everyone but can be a clever move if you’re playing the market.

Filing Strategy: When to Pick Schedule A IRS 2027 Over the Standard Deduction
Is Itemizing Worth It?
Deciding between Schedule A and the standard deduction can feel like a coin toss. For 2026 and 2027, the standard deduction is quite generous, so itemizing only makes sense if your qualifying expenses beat that number.
My experience? Most folks underestimate their deductible expenses. For more context, disability retirement pay schedule is worth reviewing. A thorough review of receipts, bills, and statements often reveals hidden deductions that tip the scales.
Watch Out for Common Pitfalls
Don’t forget: charitable contributions must be documented with receipts or bank records. Also, gambling losses can be deducted but only up to the amount of your winnings—no freebies here.
One client once tried to claim a massive donation without proof—it backfired spectacularly during an audit.
Filing Tips and Tools for Schedule A IRS 2027
Gathering Your Documents
Start early. Collect W-2s, 1098s for mortgage interest, property tax bills, medical expense statements, and receipts for charitable gifts. Organization is your secret weapon.
Use Technology to Your Advantage
Tax prep software in 2026 and 2027 has evolved to flag potential deductions on Schedule A automatically. But don’t blindly trust it—double-check entries and understand what’s being claimed.
Remember, software can guide you, but your knowledge seals the deal.

Consult a Tax Professional When in Doubt
Schedule A IRS 2027 can get complicated if you have unusual deductions or multiple properties. There’s no shame in getting a pro involved—especially if it means avoiding costly mistakes or audits.
Personal take: After years of helping clients, I’ve seen how a small consultation upfront can save thousands and headaches later. Be sure to explore semiweekly deposit schedule as well.
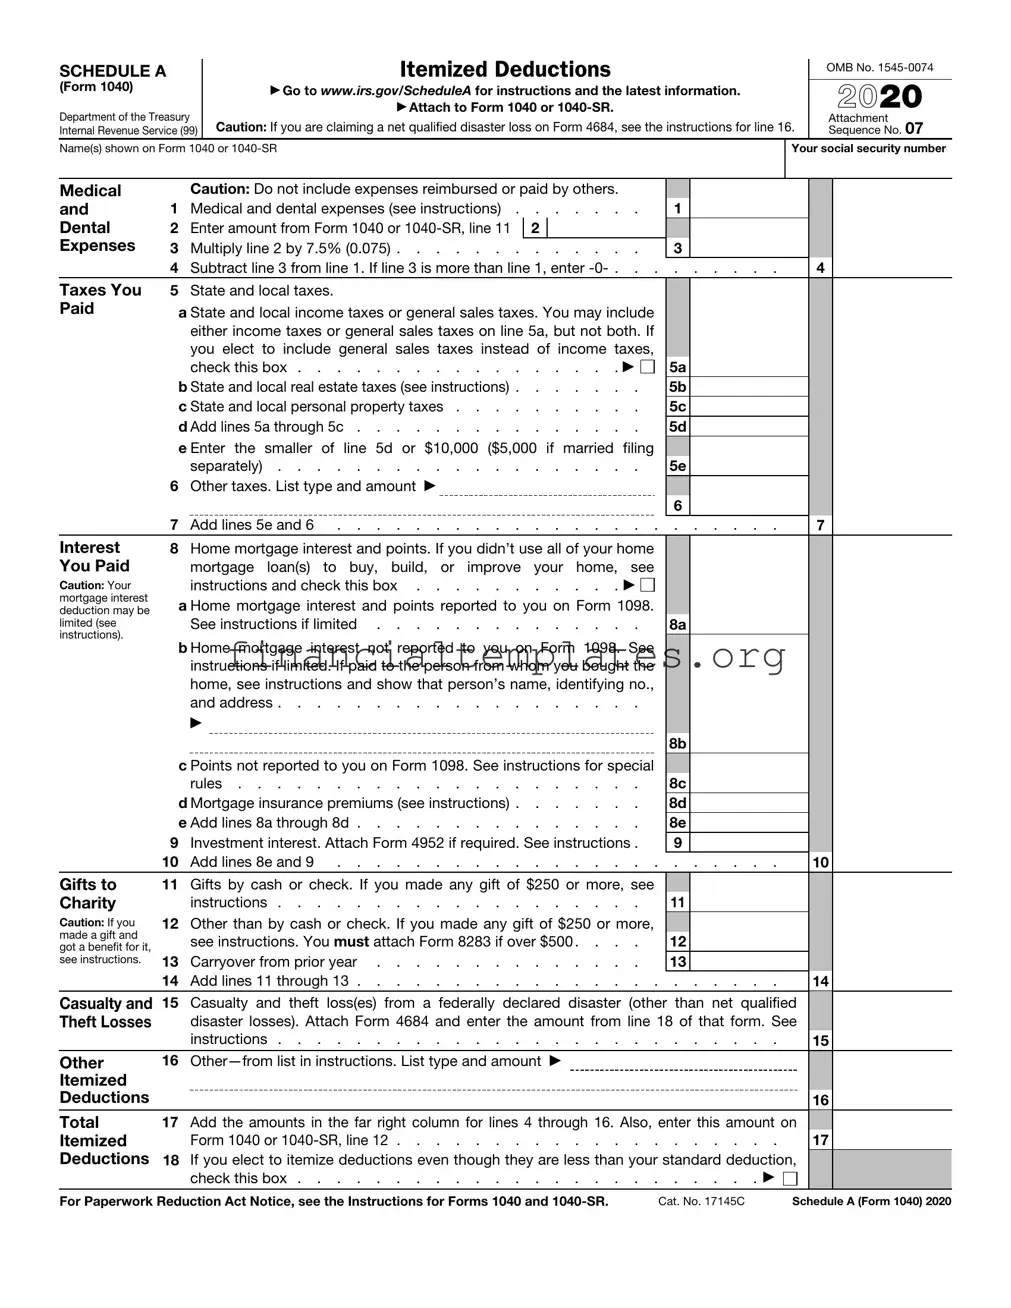
Blank IRS Schedule A 1040 or 1040-SR PDF Form ️ financialtemplates.org
Source: financialtemplates.org
Frequently Asked Questions
Who should use Schedule A IRS 2027?
If your total itemized deductions exceed the standard deduction for your filing status in 2026 or 2027, Schedule A is your go-to. Common users include homeowners, people with large medical bills, or those who made significant charitable donations.
Can I deduct all my medical expenses on Schedule A?
Only the amount exceeding 7.5% of your AGI qualifies for deduction. Keep detailed records to maximize this benefit.
Is it better to take the standard deduction or itemize?
It depends on your expenses. If your eligible deductions surpass the standard deduction, itemizing with Schedule A saves you more money.
What’s the maximum mortgage interest I can deduct?
On Schedule A IRS 2027, you can deduct interest on up to $750,000 of mortgage debt for homes purchased after December 15, 2017. Older mortgages have a $1 million cap.
Kyle Wells is a seasoned scheduling expert with over a decade of experience in optimizing time management and productivity. Passionate about helping individuals and organizations maximize their potential through effective scheduling strategies, Kyle is committed to delivering insightful content on Schedule Central.